Double Tax Treaty Withholding Lob
EU FASTER Directive (2025/50): Digital eTRCs, Certified Intermediaries, and 50-Day Quick Refunds
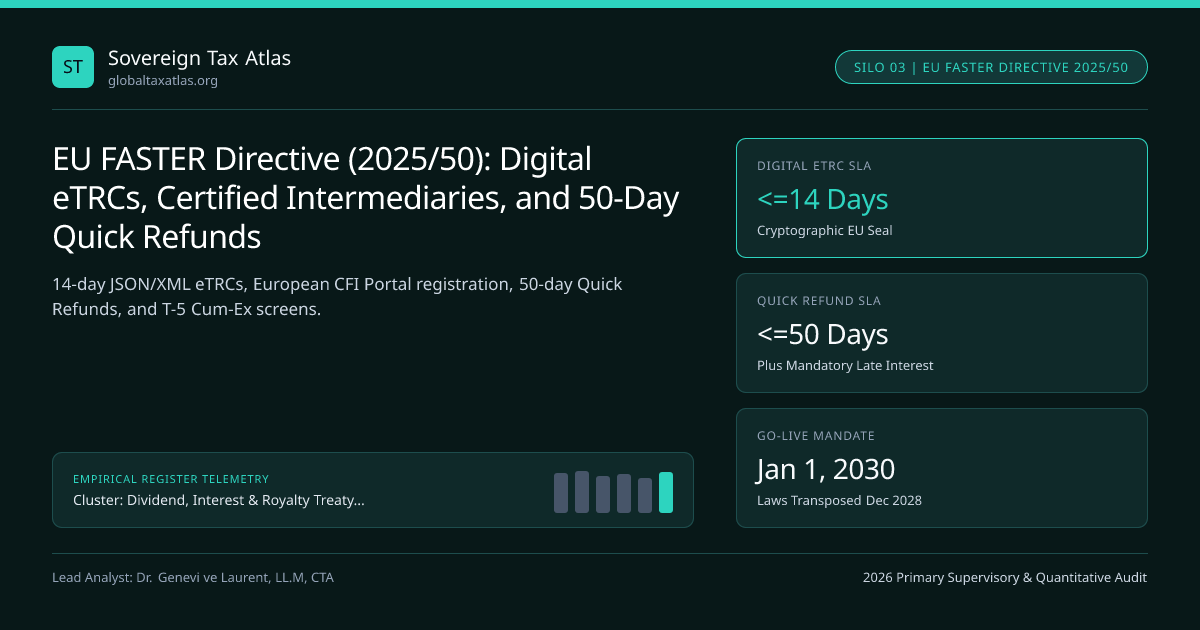
Formally adopted as Council Directive (EU) 2025/50, the EU FASTER Directive replaces multi-year paper dividend and bond withholding reclaims across Member States with standardized digital eTRCs and 50-day Quick Refunds.
Across the European Union's single capital market, cross-border equity and bond investors historically lost EUR 5.17 billion+ per year to unrecovered excess withholding taxes, administrative reclaim fees, and 2-to-5-year paper stamp delays—made even more bureaucratic after the Cum-Ex / Cum-Cum tax-fraud scandals (analyzed in securities-lending dividend rules). Formally adopted by ECOFIN and published as Council Directive (EU) 2025/50 ("FASTER" — Faster and Safer Relief of Excess Withholding Taxes), this landmark regime—benchmarked under EU FASTER Directive and the 2026 EU FASTER Benchmark Standard—anchored in our Double Tax Treaty Withholding, MLI PPT, and US LOB reference, transforms European custody across the Dividend, Interest & Royalty Treaty Withholding, PPT & LOB cluster.
Statutory Transposition & Go-Live Timeline (2028 Laws -> Jan 1, 2030 Live!)#
Track the exact statutory dates enacted in Council Directive (EU) 2025/50 (which pushed initial Commission draft dates to align custodian IT builds across all 27 Member States supervised alongside ESMA):
- December 31, 2028: Mandatory deadline for all 27 EU Member States to transpose FASTER into domestic national tax law and launch National Certified Financial Intermediary (CFI) Portals (accessible via a centralized European Certified Financial Intermediary Portal!).
- January 1, 2030: Mandatory operational go-live across all in-scope EU Member States for publicly traded equities (and optional Member State inclusion of publicly traded corporate/sovereign bonds!).
Three Structural Pillars of EU FASTER (Directive 2025/50)#
- Common EU Digital Tax Residence Certificate (eTRC — Article 4): Every EU Member State must introduce an automated system issuing a cryptographically sealed, machine-readable eTRC within 14 calendar days of request (upgraded from 1 day in early drafts to 14 days in final Council text to permit automated residence checks!), valid for at least the entire calendar year (or fiscal period) in which requested!
- National Registers of Certified Financial Intermediaries (CFIs — Articles 5–11): Large EU central securities depositories (CSDs) and systemic custodian banks must register (and non-EU custodians—in the US, UK, Switzerland, or Singapore—may voluntarily register!) as CFIs on the European CFI Portal. In return for fast relief, CFIs must transmit granular payment-chain JSON/XML reports including whether shares were acquired within 5 days before the ex-dividend date and whether any financial arrangement / securities loan / derivative linked to the dividend exists!
- Mandatory Relief at Source AND/OR Quick Refund (Articles 12–14): Every in-scope Member State (unless qualifying for the Market Capitalization Ratio <1.5% + existing comprehensive Relief-at-Source exemption!) must provide Relief at Source, a Quick Refund, or a combination of both:
- Quick Refund Window: CFIs submit the Quick Refund request within the second month following the dividend payment month, and the source tax administration MUST pay out the refund within 50 calendar days (or pay statutory late-payment interest!).
Anti-Cum-Ex Exclusions: Who Gets Shunted Out of Fast-Track Relief?#
Following German, Danish, and French Cum-Ex trauma, Member States may exclude high-risk claims from Relief at Source / Quick Refund (routing them to audited Standard Refunds instead):
- Shares acquired within 5 days prior to the ex-dividend date (T-5 anti-dividend-washing screen!);
- Dividends linked to securities lending, repo, or synthetic total-return swap arrangements (see Cum-Ex rules);
- Gross dividend payments exceeding EUR 100,000 per registered owner per payment date—WITH A MASSIVE INSTITUTIONAL EXCEPTION: regulated Collective Investment Undertakings (Irish ICAV UCITS & Luxembourg RAIF/AIF) and Statutory Pension Funds remain eligible for FASTER above EUR 100,000 under special CFI verification procedures!
Quantitative Portfolio Yield Recovery Under EU FASTER 50-Day Refunds#
- Worked EUR 1.2B Pan-European Equity UCITS Fund (Irish ICAV; 3.50% Dividend Yield = EUR 42.0M Gross Dividends Across DE, FR, IT, ES):
- Average Statutory WHT = 26.0% (EUR 10.92M) vs 15.0% Treaty Rate (EUR 6.30M) -> Excess Reclaimable WHT = EUR 4,620,000 / year!
- Legacy Paper Reclaim World (Avg 2.8-year refund lag at 8.5% equity return + 4.5% reclaim agent fee):
- Opportunity-Cost Drag on Stuck Cash = EUR 944,000/yr + EUR 207,900 Paper Reclaim Fees = EUR 1,151,900/yr lost!
- EU FASTER Regime (~60–95 days post-dividend Quick Refund + automated CFI API):
- Cuts cash-lockup cost by >85% -> Recovers ~EUR 980,000/yr (+8.2 bps net fund alpha every single year!).
EU FASTER Eligibility & Routing Matrix#
Global custodians, UCITS/AIF boards, and multi-asset execution firms—including 360 Capital, Aftermath Finance, and QI custody networks—map investor profiles against FASTER Directive 2025/50 tracks:
| Investor / Trade Scenario | Eligible for EU Digital eTRC? | Eligible for RaS / 50-Day Quick Refund? | CFI Reporting Obligation | Fallback Track |
|---|---|---|---|---|
| Retail / Family Investor (<=EUR 100k Div, Held >5d) | YES (if EU resident) | YES — Full Fast-Track! | Standard CFI chain + eTRC link | N/A |
| EU UCITS / AIF (ICAV / RAIF) (>EUR 100k) | YES | YES! (Special CIV Art. 15 verification!) | Enhanced CIV entitlement check | Standard Digital Refund |
| Non-EU Investor (US / UK / SG Pension) via Registered CFI | Uses Home TRC (non-EU) | YES! (FASTER covers Treaty + Domestic WHT!) | CFI verifies third-country TRC | Standard Digital Refund |
| Hedge Fund Buying Shares T-3 Before Ex-Date | Yes (if EU) | NO — Blocked by 5-Day Rule! | CFI flags <=5-day acquisition | Audited Standard Refund |
| Loaned Shares / Synthetic Equity Swap Hedge | Yes (if EU) | NO — Blocked by Financial-Arr. Flag! | CFI flags securities loan / swap | Audited Standard Refund |
Frequently asked questions
Can a US or UK pension fund holding French and German stocks benefit from the EU FASTER 50-day Quick Refund?
Yes! While the standardized 14-day EU eTRC is issued only by EU Member States to EU tax residents, Articles 12–14 of Directive 2025/50 open Relief at Source and 50-day Quick Refunds to non-EU investors too—provided they hold shares through a registered Certified Financial Intermediary (CFI) and furnish equivalent non-EU residence proof (such as IRS Form 6166)!
Which EU Member States can opt out of building the new Quick Refund system under the <1.5% Market Capitalization exemption?
A Member State that ALREADY operates a comprehensive Relief-at-Source system AND has a national stock-market capitalization ratio below 1.5% of total EU market cap across four consecutive years (monitored via ESMA data) may keep its national RaS system—unless its RaS processing exceeds strict timelines.
Why are Certified Financial Intermediaries (CFIs) worried about Article 16 civil liability under FASTER?
Article 16 holds CFIs liable for all or part of lost withholding tax revenue if the CFI intentionally or negligently fails due-diligence verification (such as failing to detect a client 5-day pre-ex-date wash purchase or unflagged securities loan)—driving massive custodian regtech investment!
Does EU FASTER cover corporate and government bond interest withholding or only listed equities?
FASTER is strictly mandatory across Member States for dividends on publicly traded shares, while giving each Member State the explicit statutory option to include interest on publicly traded bonds inside the exact same CFI Relief-at-Source and 50-day Quick Refund rails.
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Dr. Geneviève Laurent, LL.M, CTA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Geneviève Laurent, LL.M, CTA. (2026, November 14). EU FASTER Directive (2025/50): Digital eTRCs, Certified Intermediaries, and 50-Day Quick Refunds. Sovereign Tax Atlas. https://globaltaxatlas.org/entries/eu-faster-directive-digital-etrc-relief-at-source-quick-refundRegulatory Directory Cross-Reference
Referenced Institutions & Regulatory Registries
Top Regulated Institutions in This Coverage Slice
Referenced Supervisory Authorities
Related Double Tax Treaty Withholding Lob & Institutional Briefings
Explore Double Tax Treaty Withholding Lob Hub (20) →Double Tax Treaty Withholding Lob
Double Tax Treaty Withholding Rates, OECD MLI Principal Purpose Test, and US LOB ReferenceDouble Tax Treaty Withholding Lob
Switzerland 35% Verrechnungssteuer Refunds: Form 823 Notification at Source and the "Old Reserves" TrapDouble Tax Treaty Withholding Lob
US–UK Double Tax Treaty Article 10(3): Qualifying for 0% Subsidiary and Pension Dividend WithholdingDouble Tax Treaty Withholding Lob
US–Ireland Tax Treaty 15% Dividend Withholding: Why Irish ICAV UCITS Dominate Global ETFsDouble Tax Treaty Withholding Lob
US Portfolio Interest Exemption (IRC 871(h) & 881(c)): 10% Shareholder Attribution and Bank TrapsDouble Tax Treaty Withholding Lob
US IRC Section 871(m) Dividend Equivalents: Delta-One Swaps, Notice 2024-44, and Qualified IndicesDouble Tax Treaty Withholding Lob
US IRC Section 892 Sovereign Wealth Fund Tax Exemption: Controlled Entities and Commercial TaintDouble Tax Treaty Withholding Lob
EU Parent-Subsidiary and Interest-Royalties Directives After the ECJ Danish Beneficial Ownership CasesEconomic Substance Cfc Transfer Pricing
UK TIOPA 2010 Part 9A CFC Regime: Chapter 3 Gateways, 75% Tax Exemption, and Chapter 9 Finance Company RulesEconomic Substance Cfc Transfer Pricing
OECD Transfer Pricing Guidelines Chapter VI: Intangible DEMPE Functions vs Legal IP OwnershipEconomic Substance Cfc Transfer Pricing
Hard-to-Value Intangibles (HTVI): Ex-Post Outcomes, the 20% Valuation Corridor, and Price AdjustmentsEconomic Substance Cfc Transfer Pricing
OECD Pillar One Amount B (2025+): Baseline Wholesale Marketing and Distribution Return-on-Sales Matrix
Sovereign Tax Atlas Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.